

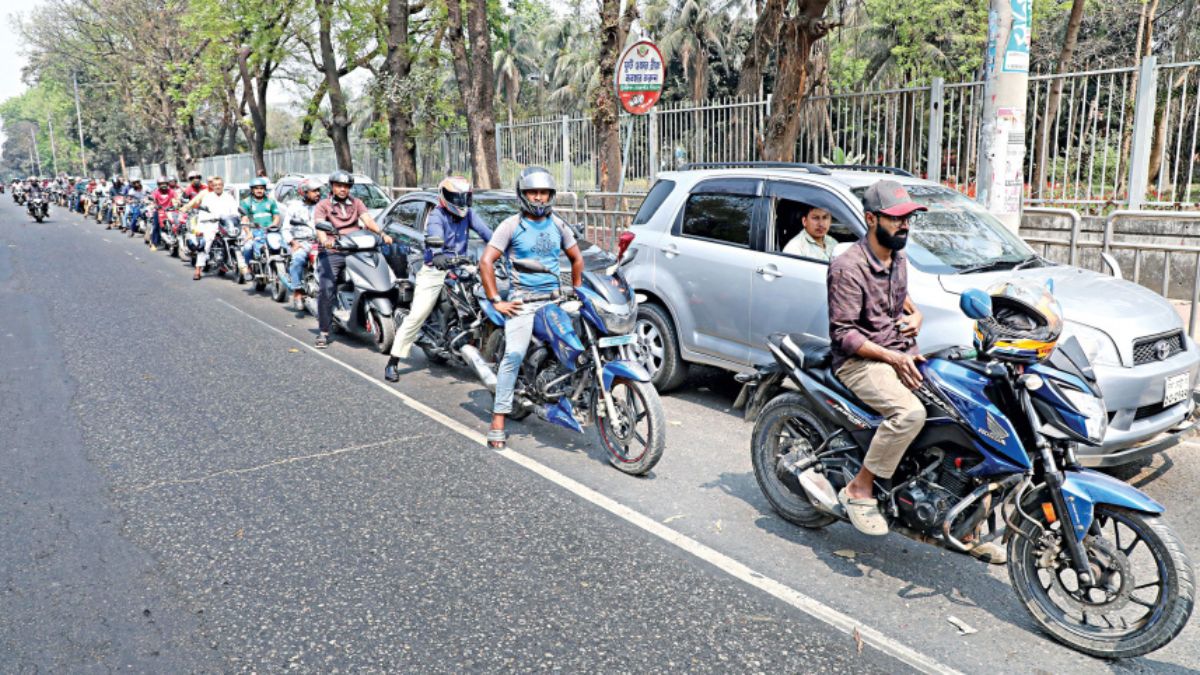
Bangladesh is confronting severe macroeconomic headwinds after years of structural mismanagement. Among the most critical challenges is the country’s energy sector, where long-standing systemic flaws have been further amplified by global geopolitical tensions.
The repercussions of the energy crisis now reach far beyond the power grid; they pose a direct threat to overall macroeconomic stability. Consequently, the crisis can no longer be treated solely as a matter for the Ministry of Power, Energy and Mineral Resources. To avert a broader economic fallout, the Ministry of Finance and Bangladesh Bank must fully integrate energy sector dynamics into the national macroeconomic framework and coordinate policy accordingly.
The Ripple Effects on the Macroeconomy
The spillover effects of the energy crisis across the wider economy are underscored by three critical trends:
Surging Import Bills: Driven by domestic supply shortfalls and volatile global commodity markets, the energy import bill escalated from $4.3 billion in FY2021 to $11.2 billion in FY2026. This rapid expansion poses a severe threat to Bangladesh’s balance of payments (BoP).
Unsustainable Subsidy Burdens: The energy subsidy bill expanded from Tk 142 billion (0.4% of GDP) in FY2021 to Tk 837 billion (1.5% of GDP) in FY2025. With the tax-to-GDP ratio standing at a mere 6.8% in FY2025, energy subsidies alone consumed roughly 22% of total tax revenue. While recent price adjustments have provided temporary relief, fluctuating global energy prices risk eroding these gains.
Erosion of Industrial Competitiveness: Energy shortages and rising tariffs have weakened export competitiveness, disrupted manufacturing and logistics, and slowed GDP growth. This broader economic deceleration has also emerged as a primary driver of rising non-performing loans (NPLs) within the banking system.
Systemic Root Causes
The structural vulnerabilities in the energy sector stem from several deeply entrenched issues:
Over-reliance on state-dominated energy production and distribution
Mismanaged and inefficient state-owned enterprises (SOEs)
Flawed pricing policies and the absence of a coherent primary energy strategy
Political interference, lack of hard budget constraints, and corruption in contract awards—particularly regarding Independent Power Producers (IPPs)
Weak operational transparency and accountability
Continuing with piecemeal adjustments and short-term crisis management is no longer a viable option. Comprehensive structural reform is required to place the sector on a sustainable trajectory.
Key Strategic Pillars for Reform
To achieve meaningful and lasting progress, policymakers should focus on six core reform areas:
┌─────────────────────────────────────────────────────────┐
│ CORE ENERGY SECTOR REFORM PILLARS │
└────────────────────────────┬────────────────────────────┘
│
┌───────────────────┬──────────────────────┼──────────────────────┬───────────────────┐
│ │ │ │ │
┌───┴──────────┐ ┌──────┴───────────┐ ┌────────┴───────────┐ ┌────────┴──────────┐ ┌───┴───────────┐
│ Deregulation │ │ Governance Reform │ │ IPP Renegotiation │ │ Depoliticization │ │ Primary Energy│
│ & Private │ │ & Corporatization │ │ of Contracts │ │ of Pricing │ │ Strategy │
│ Sector Entry │ │ of Public SOEs │ │ │ │ │ │ Development │
└──────────────┘ └───────────────────┘ └───────────────────┘ └──────────────────┘ └───────────────┘
1. Full Deregulation Across the Value Chain
While private participation has grown in power generation, state enterprises continue to dominate the market. Opening every stage of the value chain—from oil and gas exploration, refining, and imports to power generation and distribution—will attract private capital, drive efficiency, and reduce the long-term burden on public finances.
2. Corporate Governance in State-Owned Enterprises
Because transitioning to a market-led system takes time, existing public energy enterprises require immediate governance overhauls. Key measures should include:
Full corporatization under professional, non-political management
Operational autonomy regarding procurement, employment, and investment decisions
Enforcement of hard budget constraints paired with transparent, target-oriented subsidies
3. Restructuring Independent Power Producer (IPP) Contracts
Overly optimistic demand projections and flawed capacity planning have resulted in costly “take-or-pay” commitments that strain public finances. IPP contracts must be renegotiated on transparent, commercial terms to align with real market conditions and restore financial balance to the power sector.
4. Depoliticizing Pricing & Developing Primary Energy Strategy
Establishing market-reflective pricing mechanisms will reduce fiscal exposure to price shocks. Concurrently, developing a clear, long-term primary energy strategy will provide investors with certainty and ensure a reliable energy mix for the future.